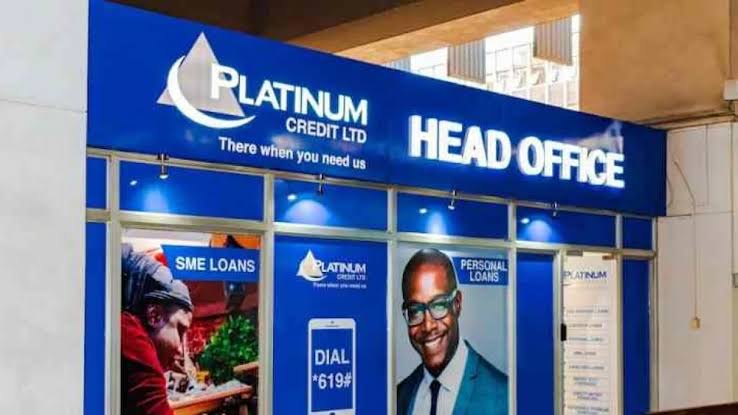

Platinum Credit has turned Kenyan phone numbers into open hunting grounds, sending loan texts and calls to people who never applied, never consented and never gave the company their details in the first place.
The practice is so widespread that ordinary citizens now spend time blocking numbers and filing complaints, yet the messages keep coming. One recent case shared widely on social media shows the Office of the Data Protection Commissioner ordering the firm to pay Samuel Kamau Waweru Ksh 400,000 after agents used his personal data for repeated loan promotions without his knowledge or permission.
That order is not an outlier. It sits inside a longer pattern of aggressive outreach that has become part of how this lender finds new customers.
The company has operated in Kenya for more than twenty years. It started with a simple offer of fast emergency cash for civil servants, teachers and salaried workers, and it still sells that speed today.
Loans are promised within twenty-four hours. The branch network stretches past one hundred outlets. Products include logbook loans, salary check-off facilities, personal credit and business financing.
The firm is licensed by the Central Bank as a digital credit provider and belongs to a larger regional group that has attracted development funding for expansion. On the surface it looks like a solid microfinance player delivering quick money across the country.
The reality of how it reaches people is far less polished.
Sales agents and call centres dial numbers that never appeared on any application form. Callers sometimes quote vehicle details or other private information the recipient never shared with Platinum Credit.
When people ask how their data was obtained or request that contact stop, the responses are often thin or the calls simply continue under different numbers.
Public posts and formal complaints describe the same experience over and over: phones lighting up with loan offers from a company the owner has never dealt with.
In the case involving Samuel Kamau, investigators found that the agent who contacted him was linked to the firm even after the company initially denied any connection.
The regulator also recommended that directors face possible prosecution for supplying false information during the probe.
This is not limited to one complaint. Other individuals have reported the same treatment, with some cases resulting in higher compensation awards and enforcement notices.
The Data Protection Act requires clear consent before personal information is used for commercial marketing. It also requires firms to respect requests to stop contact and to erase data when asked.
The volume of unwanted messages shows how often those requirements are ignored. Platinum Credit’s size makes the problem more visible, but the same methods appear across the digital lending industry.
Numbers change hands, consent is treated as optional, and the right to privacy becomes secondary to the need for new borrowers.
The business model depends on constant pipeline of customers. Speed is the selling point, and aggressive contact is how many of those customers are found.
Interest rates and extra fees vary by product. Logbook loans carry additional costs for valuation, tracking devices and registration. Check-off arrangements with formal employers make repayment automatic and reduce risk for the lender.
That model works well for the company. It works less well for the thousands of people whose phones become marketing targets without their agreement.
Public frustration has grown because the experience is so common. A new line can start receiving loan messages within days. Old numbers that once belonged to someone else keep attracting calls about debts the current owner never took. Agents keep dialling. Texts keep arriving.
The regulator has issued findings and ordered compensation in several cases, yet the wider practice continues. Each new complaint underlines the gap between the law and the daily reality of unsolicited contact.
Platinum Credit presents itself as a customer-focused lender with a large physical presence and a record of rapid disbursement. Its parent group speaks of supporting small businesses and women entrepreneurs. Those claims sit beside a growing list of data protection cases that show how the company finds and contacts potential clients.
The tension is plain. Rapid growth and respect for personal data do not currently sit comfortably together.For ordinary Kenyans the practical reality is clear. Once a number enters a marketing list it can be difficult to remove.
The law offers a path for complaint and, in some cases, for compensation, as the order in favour of Samuel Kamau demonstrates.

Add Comment